Quick answer: The four main ways to fund a remodel are a home equity loan (fixed lump sum, lowest rates), a HELOC (revolving line, best for phased projects), a personal loan (no collateral, fast, best for $5,000–$25,000), and contractor financing (fastest, most convenient). With 20%+ equity and a project over $25,000, home-equity options usually win on rate; for smaller or faster jobs, a personal loan often makes more sense (U.S. Bank, 2026).
This guide is educational and not financial advice. Rates are approximate and change often — as of mid-2026 — so compare lenders and consult a financial professional for your situation.
Key Takeaways
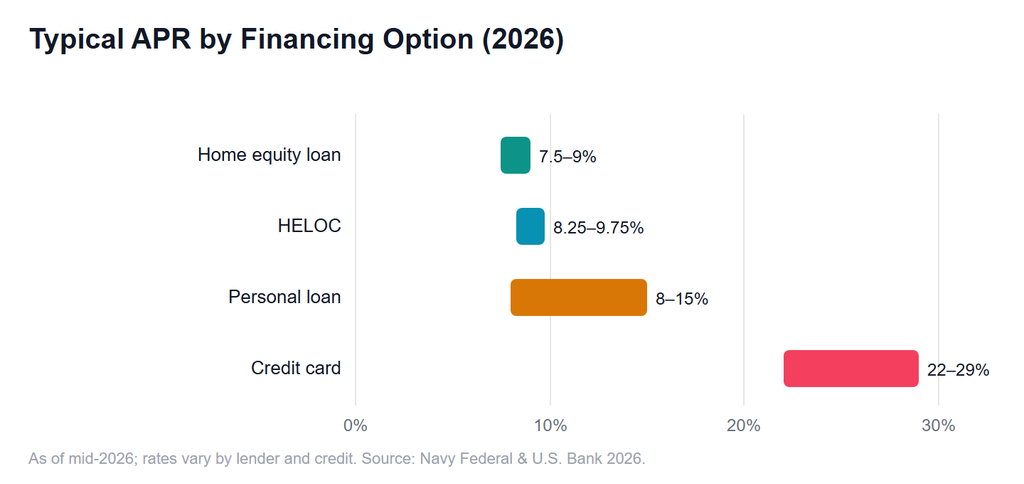
- Home equity loan: fixed rate (often 0.5–1% below a HELOC), lump sum, closing costs $2,000–$5,000 (U.S. Bank, 2026).
- HELOC: revolving line around 8.25–9.75% (variable), ideal for phased projects (Navy Federal, 2026).
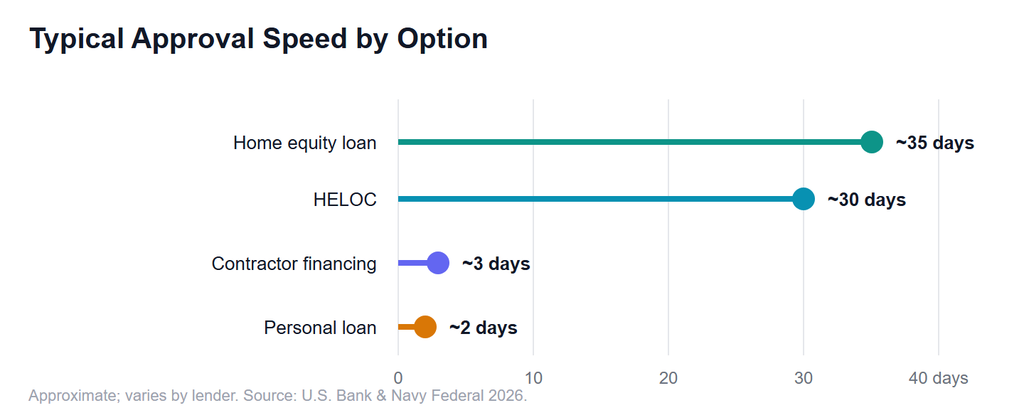
- Personal loan: ~8–15% for good credit, no collateral, approval in 1–3 days.
- Avoid credit cards for big jobs — 22–29% is far costlier.
- Match the loan to the project: known scope → home equity loan; phased → HELOC; $5K–$25K quick job → personal loan.
What’s the best way to finance a home remodel?
There’s no single best option — the right choice depends on your equity, credit, project size, and timeline. The biggest cost difference is the interest rate, and it’s dramatic: home-equity products currently run in the 7–10% range, personal loans 8–15%, and home-improvement credit cards a punishing 22–29% (Navy Federal, 2026).
Home equity loan: best for a known budget
A home equity loan gives you a fixed-rate lump sum secured by your home — you know your payment from day one. Rates typically run 0.5–1% below a HELOC, and closing costs are $2,000–$5,000 (U.S. Bank, 2026). It’s the textbook fit for a project with a firm contractor bid and a defined scope — a kitchen gut-renovation, say, where you know the number up front. You’ll want 20%+ equity to qualify for the best terms.
HELOC: best for phased projects
A home equity line of credit (HELOC) is a revolving line you draw from as needed during a draw period (typically 5–10 years). Variable rates currently sit around 8.25–9.75% for qualified borrowers — well below credit cards (Navy Federal, 2026). A HELOC shines for a multi-phase remodel that unfolds over 12–18 months, since you only pay interest on what you actually draw. The trade-off is a variable rate that can move over time.
Personal loan: best for smaller, faster jobs
A personal loan doesn’t use your house as collateral, which means faster approval (often 1–3 days), no appraisal, and no closing costs — and no risk to your home. The trade-off is a higher rate, typically 8–15% for borrowers with good credit (700+) (Navy Federal, 2026). Personal loans make the most sense for projects in the $5,000–$25,000 range, or when you don’t have much equity yet.
Contractor financing: best for convenience
Many contractors — including Good Vibes Construction, through our GreenSky financing partner — offer one-stop financing that closes fast (often 1–5 days). The convenience is real: you handle the project and the payment plan in one place. The honest trade-off is the rate. Compare the contractor’s offer to an independent quote: if it’s within 1–2 percentage points, the convenience is often worth it; if the spread is 5+ points, you’re paying a premium for the ease.
Which option fits your project?
Use this quick comparison to match the financing to your situation:
| Option | Typical rate | Collateral | Speed | Best for |
|---|---|---|---|---|
| Home equity loan | ~7.5–9% (fixed) | Your home | ~2–5 weeks | Known scope, firm bid, 20%+ equity |
| HELOC | ~8.25–9.75% (variable) | Your home | ~2–5 weeks | Phased projects over 12–18 months |
| Personal loan | ~8–15% | None | 1–3 days | $5K–$25K, little equity, speed |
| Contractor financing | Varies (compare) | Varies | 1–5 days | Convenience, one-stop process |
The pattern most homeowners land on: 20%+ equity and a $25,000+ project → home-equity loan or HELOC for the best rate; smaller or faster jobs → a personal loan or contractor financing for speed and simplicity.
What credit score and equity do you need?
For the best rates, lenders generally look for a credit score of 700+ and, on home-equity products, at least 20% equity in your home. You can still qualify with less, but expect higher rates or lower limits. Before applying, check your credit, estimate your equity (home value minus what you owe), and get a firm project estimate so you borrow the right amount.
Knowing your number first also helps you choose the loan. Our cost guides for a kitchen remodel, bathroom remodel, and home addition remodel can help you set a realistic budget before you talk to a lender.
Frequently asked questions
What’s the best way to finance a home remodel? It depends on your equity, project size, and timeline. For a known scope with 20%+ equity, a fixed-rate home equity loan usually offers the best rate; for a phased project, a HELOC; for a smaller or faster job, a personal loan or contractor financing.
Is a HELOC or home equity loan better for a renovation? A home equity loan is better when you know the exact cost up front and want a fixed payment. A HELOC is better for a multi-phase project because you draw (and pay interest) only as you need it. HELOC rates are variable; home equity loan rates are fixed.
Can I finance a remodel with no equity? Yes — a personal loan or contractor financing doesn’t require home equity, since it isn’t secured by your house. Expect a higher rate (typically 8–15% for good credit) than an equity-based option, and faster approval.
Is contractor financing worth it? It can be, for the convenience of a one-stop process and fast approval. Compare the contractor’s rate to an independent quote: within 1–2 percentage points, the convenience is often worth it; a 5+ point spread means you’re paying a premium.
What credit score do I need to finance a remodel? A score of 700+ generally unlocks the best rates on personal loans and home-equity products. You can qualify with a lower score, but expect higher rates or smaller limits.
Ready to plan (and price) your remodel?
Good Vibes Construction is a licensed and insured remodeler (RCE 69010) serving Boise, Nampa, Meridian, Caldwell, Eagle, Kuna, Middleton, and Star. We provide transparent, line-item estimates so you can finance the right amount with confidence — and we offer financing through GreenSky if one-stop convenience is what you’re after.
Get your free, itemized remodel estimate →
Price your project first with our cost guides: kitchen remodel cost · bathroom remodel cost · whole-home remodel cost · interior remodeling.
Sources
- Navy Federal Credit Union — Home Equity Loan vs. HELOC vs. Personal Loan: Which Is Best? navyfederal.org (retrieved 2026-07-15)
- U.S. Bank — How Home Improvement Loans Work and Financing Options. usbank.com (retrieved 2026-07-15)
- Bankrate — Home Equity Rates and the 2026 Rate Environment. bankrate.com (retrieved 2026-07-15)